MENA FinTech Venture Capital: The H1 2026 Review
FinTech is becoming an increasingly important pillar of MENA’s financial ecosystem, as digital payments, banking infrastructure, lending, open banking, and other technology-driven financial services reshape how consumers and businesses access and use financial products.
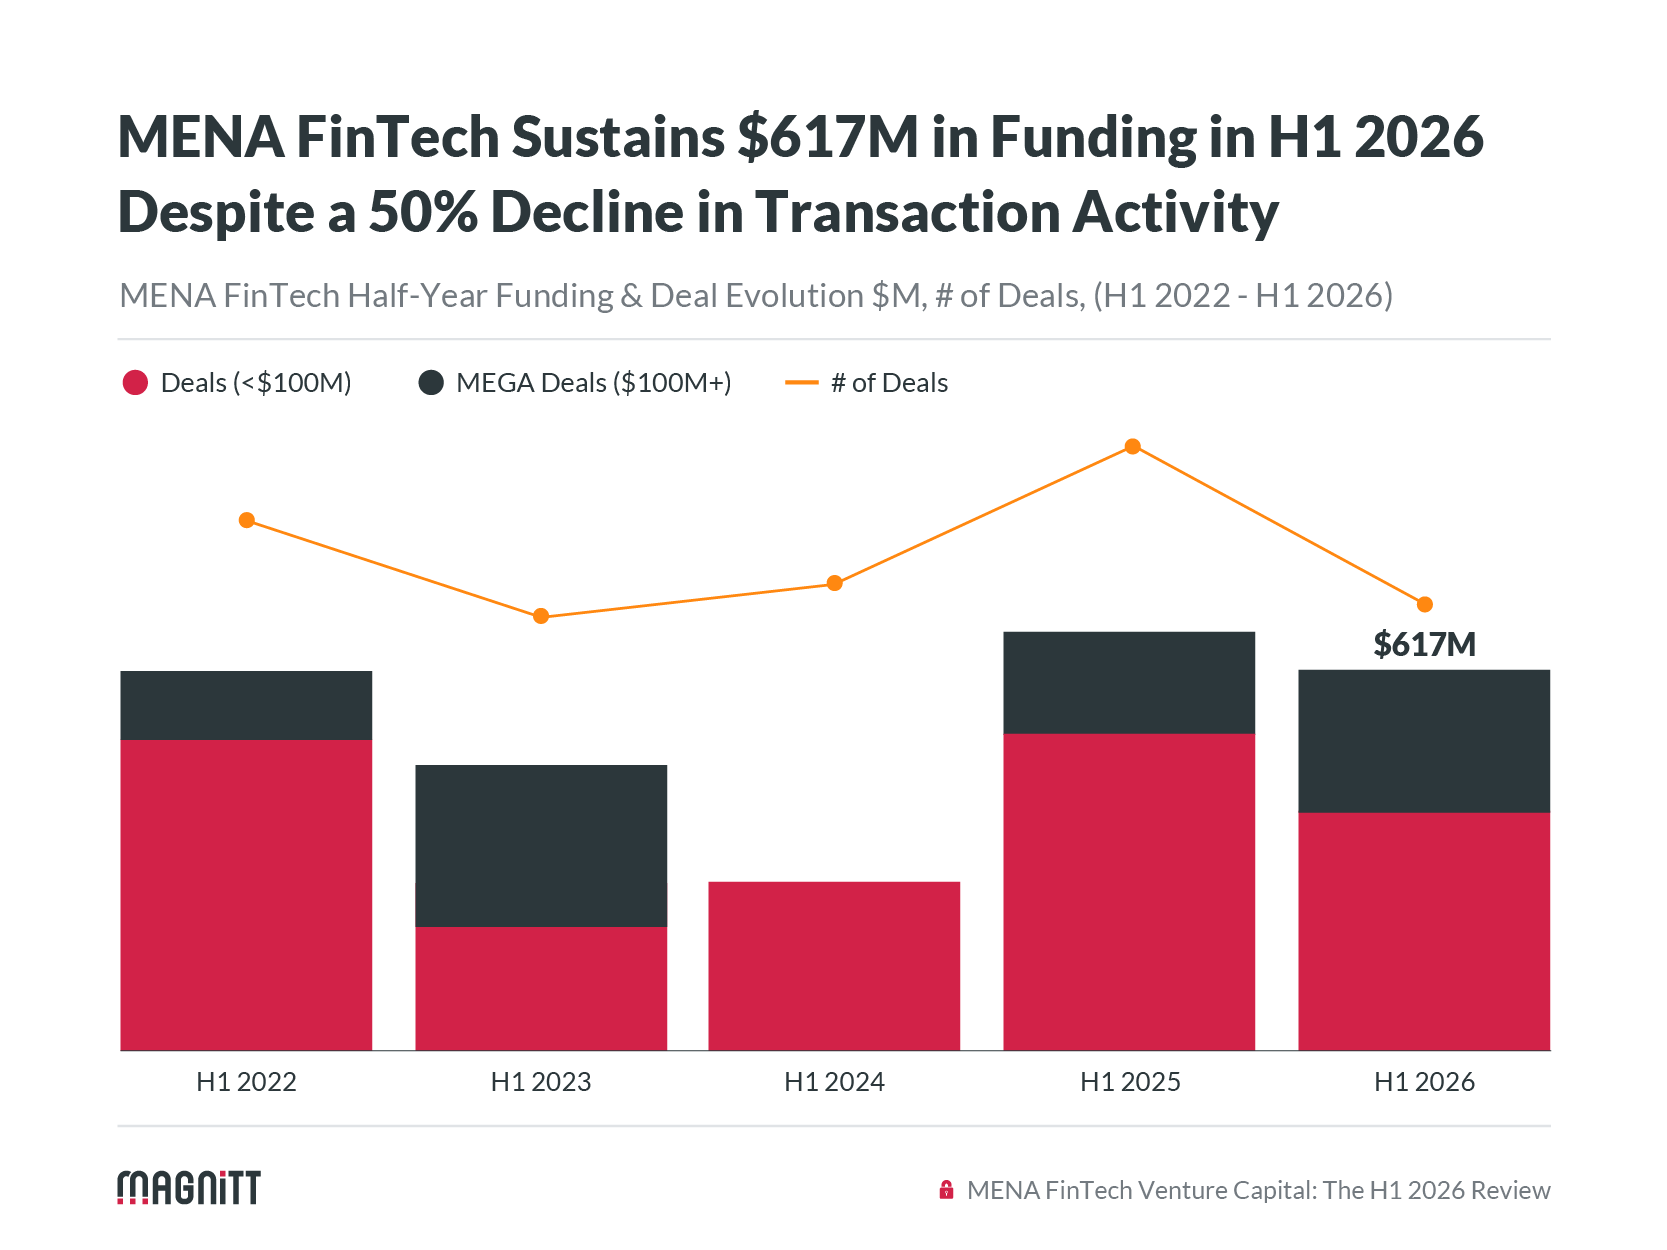
In H1 2026, MENA FinTech companies raised $617M across 57 transactions, with funding down 9% YoY and transaction activity falling 50%. This divergence highlights a growing concentration of capital in larger deals and a more selective funding environment.
Drawing on verified MAGNiTT platform data, this report provides a comprehensive view of MENA’s FinTech landscape, covering funding trends across markets and sub-industries, investor participation, transaction sizes, funding stages, and exit activity. Together, these insights show where FinTech capital is flowing and the trends shaping the sector’s next phase.
📊 Key Takeaways
- Funding remained broadly in line YoY, while deal activity declined. MENA FinTech funding reached $617M in H1 2026, broadly in line with the $679M raised in H1 2025, despite a 50% decline in transaction activity.
- Larger deals drove MENA FinTech funding in H1 2026. The market saw a notable concentration of capital in larger transactions, with 11% of deals exceeding $20M and a further 33% of transactions falling within the $5M–$20M range, the highest share recorded over the period.
- The UAE and Saudi Arabia captured 85% of MENA FinTech funding. Together, the two markets raised $523M in H1 2026. UAE FinTech funding increased 14% YoY, while Saudi Arabia recorded a 41% decline.
- Payment Solutions led FinTech deal activity. Despite a 45% decline in Payment Solutions transactions, it still recorded the highest number of deals among FinTech sub-industries in H1 2026.
- Local investors dominated the FinTech landscape. Regional investors accounted for 64% of active investors and 81% of capital deployed in H1 2026, while international investor participation declined.
🎯 Who Should Read This Report
This report is for those tracking where FinTech capital is flowing across MENA, and which parts of the ecosystem are gaining momentum.
- Investors and LPs assessing where FinTech capital is being deployed, how concentrated funding has become, and which markets and sub-industries are attracting investor attention.
- Founders understanding shifts in transaction sizes, funding stages, investor participation, and where capital remains available across MENA’s FinTech ecosystem.
- Policymakers and ecosystem builders monitoring the development of FinTech across key MENA markets and the sectors driving financial innovation.
- Advisors and consultants seeking a data-driven view of MENA’s FinTech landscape, including funding trends, deal activity, sub-industry dynamics, investor participation, and exits.
Where is this data from?
The report was created using MAGNiTT's proprietary data platform, the leading VC and PE intelligence platform across the Middle East, Africa, Pakistan, Türkiye, and Southeast Asia. With data on 34,800+ startups, 22,500+ funding rounds, and 1,300+ exits, MAGNiTT provides one of the region's most comprehensive technology datasets.
The MGTI combines MAGNiTT's proprietary venture intelligence with publicly available market data, including exchange filings, company disclosures, share prices, free-float market capitalisation, liquidity metrics, and benchmark indices. Updated quarterly, the index provides a transparent and consistent measure of MENA's listed technology sector.
Learn how MAGNiTT can help your business today!