MENA Venture Capital: The Q3 2026 Update
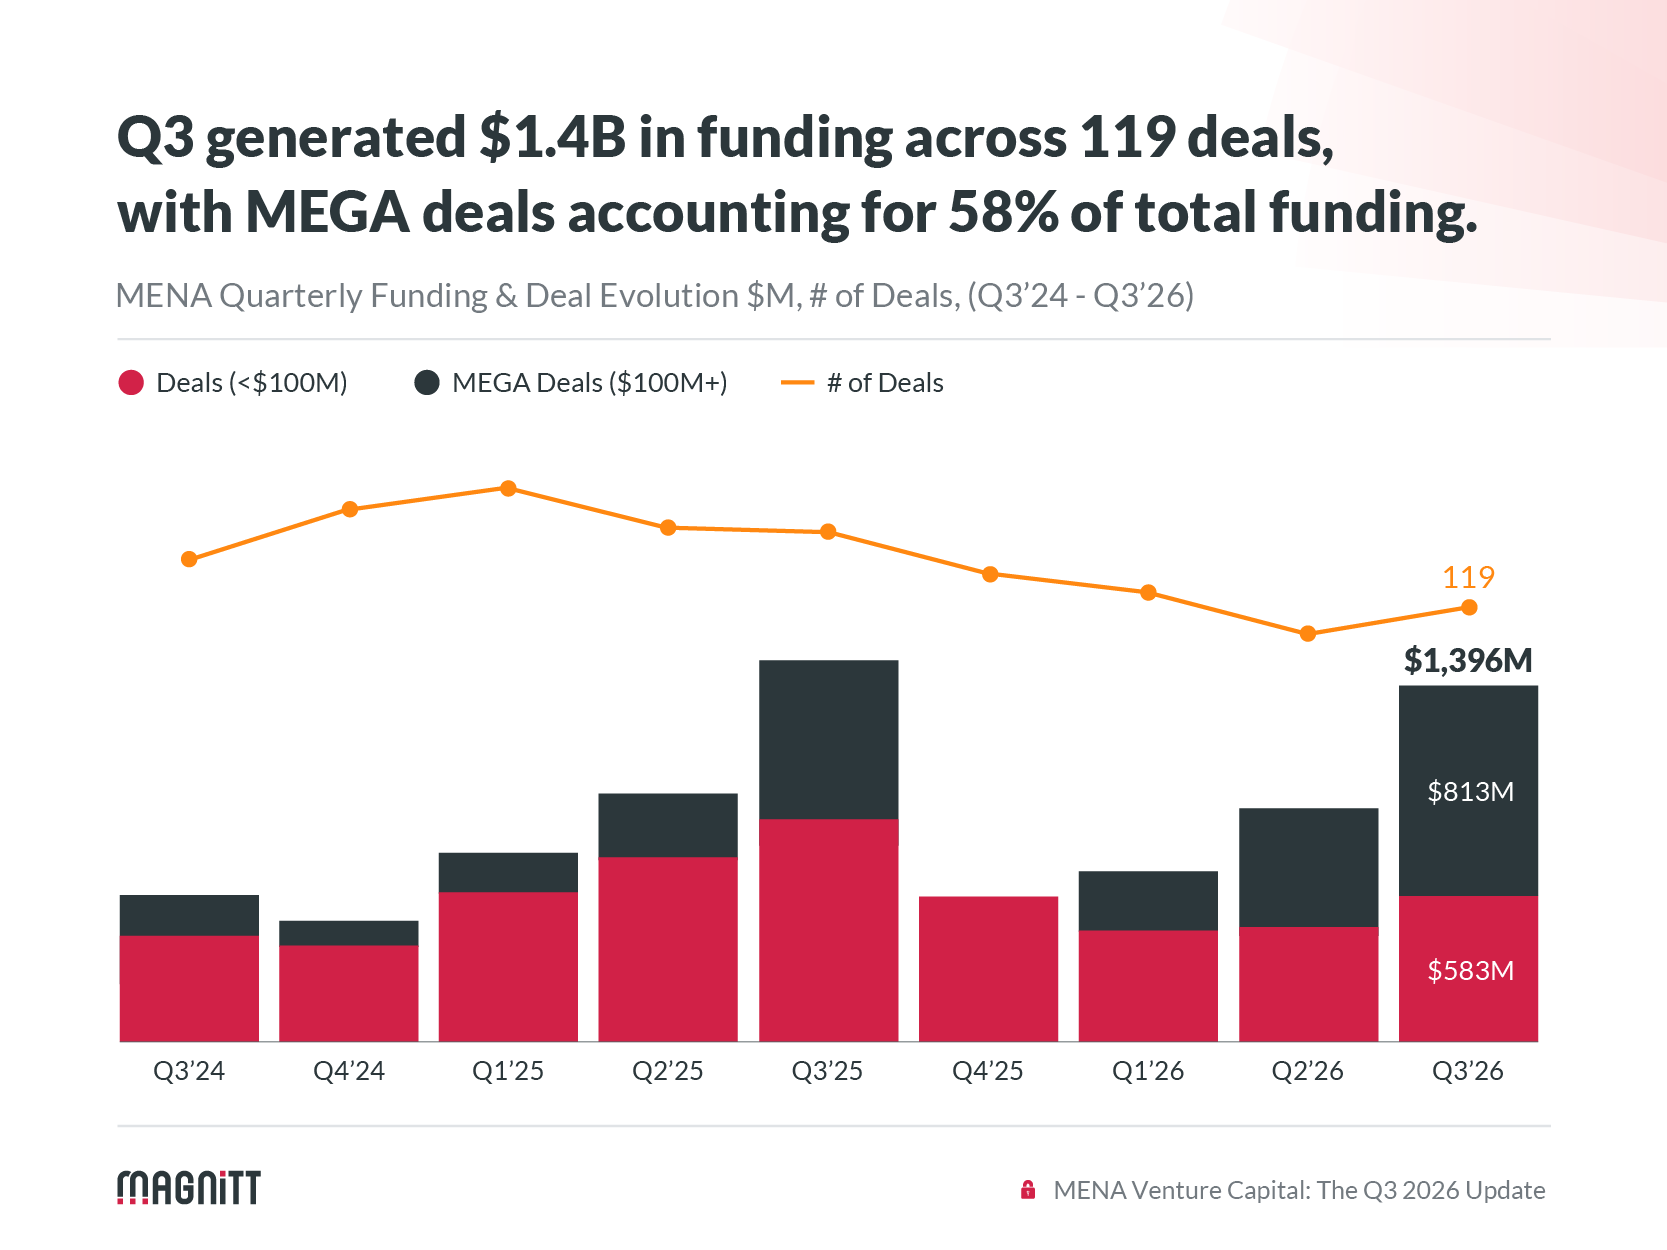
Nine months into 2026, the effects of the conflict are increasingly reflected in MENA’s venture capital data, with the market facing mounting pressure and mirroring broader global trends. While funding remained supported by fewer, larger MEGA deals, overall deal activity declined sharply, highlighting a more concentrated funding environment.
Despite a slight YoY decline in funding levels, this resilience is increasingly driven by MEGA deals, while the sharp decline in deal activity presents a growing pipeline risk for Q4 and 2027. Fewer new companies entering the ecosystem today could translate into fewer businesses progressing to later-stage funding rounds. In Q4, ecosystem events and government-backed initiatives could help support deal formation and investor engagement, but sustained momentum will depend on broader recovery in venture activity.
This report provides an overview of MENA’s VC landscape through 9M 2026, with a focus on Q3. It examines funding and deal activity, investor participation, sector trends, capital concentration, and M&A liquidity, offering insight into how the region’s venture ecosystem is evolving.
📊 Key Takeaways
- Funding held up better than deal activity: 9M 2026 MENA funding declined 7% YoY, while deal activity recorded a much sharper decline of 33%, pointing to greater concentration of capital across fewer transactions.
- Early-stage deals at a decade low: Early-stage transactions accounted for 82% of MENA deal activity in 9M 2026, maintaining the majority share but falling to their lowest level in a decade, signaling a weakening pipeline for future funding rounds.
- Investor participation shifted toward local capital: Overall investor activity declined in 9M 2026, driven in part by lower international participation, while local investors increased their relative contribution and helped cushion the decline in capital deployment.
- UAE and Saudi Arabia remained the region’s largest VC markets: The UAE attracted the highest funding and transaction activity across MENA, closely followed by Saudi Arabia. Together, the two markets accounted for 89% of total regional funding.
- M&A liquidity remained under pressure: In line with global M&A performance, MENA M&A activity declined 26% YoY, while Egypt increased its share of regional M&A activity to 35%.
🎯 Who Should Read This Report
This report is for investors, fund managers, and founders tracking how MENA venture capital is evolving in 9M 2026, where funding is holding up, and how deal and investor activity are shifting
- Limited Partners and institutional investors assessing how regional and international capital is deploying across MENA amid changing market conditions.
- General Partners and venture investors benchmarking deal flow, funding concentration, investor participation, and market activity against the wider region.
- Founders gauging which stages, sectors, and markets continue to attract capital as deal activity contracts.
- Corporates, policymakers, and ecosystem builders monitoring shifts in MENA’s venture ecosystem, including funding, investor participation, and M&A liquidity.
Where is this data from?
The report was created using MAGNiTT's proprietary data platform, the leading VC and PE intelligence platform across the Middle East, Africa, Pakistan, Türkiye, and Southeast Asia. With data on 34,800+ startups, 22,500+ funding rounds, and 1,300+ exits, MAGNiTT provides one of the region's most comprehensive technology datasets.
The MGTI combines MAGNiTT's proprietary venture intelligence with publicly available market data, including exchange filings, company disclosures, share prices, free-float market capitalisation, liquidity metrics, and benchmark indices. Updated quarterly, the index provides a transparent and consistent measure of MENA's listed technology sector.
Learn how MAGNiTT can help your business today!