MENA FinTech funding holds at $617M as transactions activity drops sharply
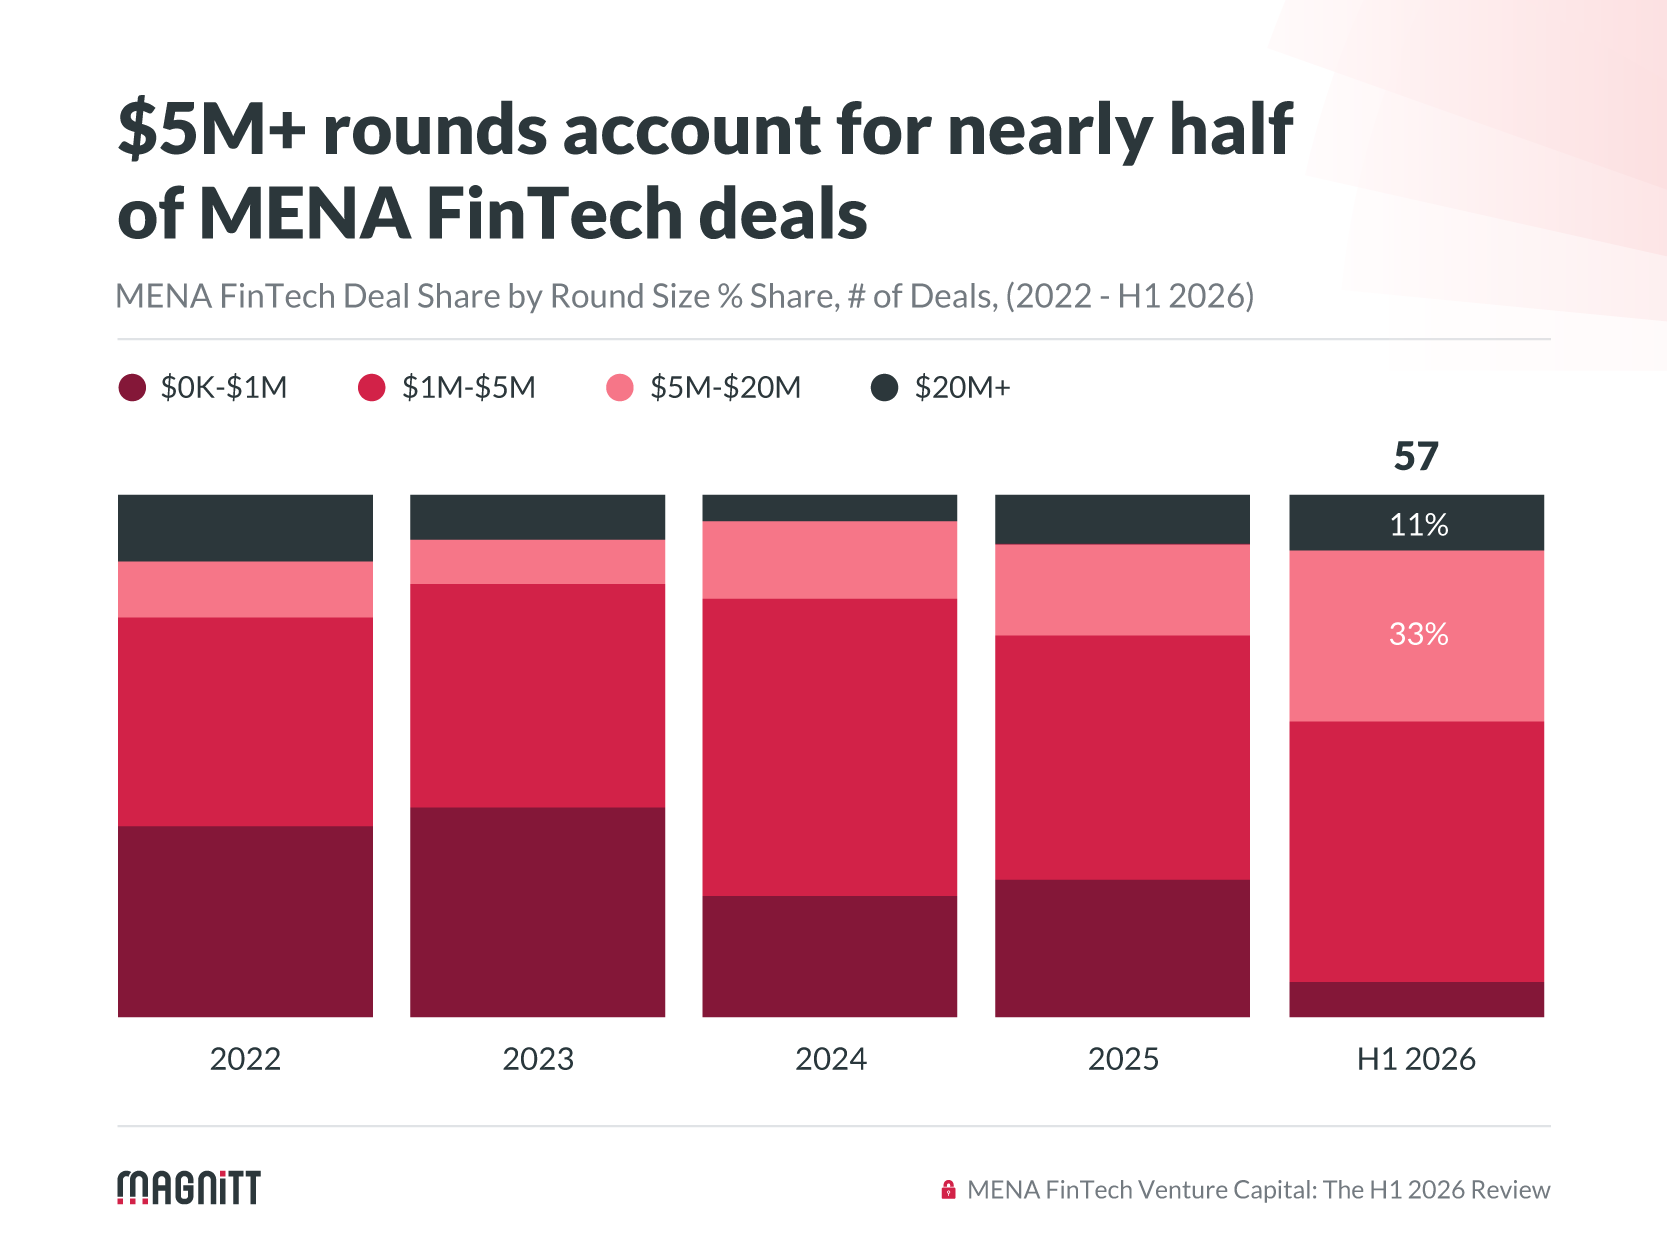
FinTech companies in MENA raised $617M across 57 transactions in H1 2026, matching the H1 2022 funding total but across 31 fewer deals. The gap between capital deployed and deal activity points to a market where funding remains concentrated among fewer transactions, with larger rounds accounting for an increasing share of total capital.
The decline in deal activity is even more pronounced compared with H1 2025. Transactions fell 50% YoY to 57, making H1 2026 the second-lowest first half for FinTech transactions over the period, ahead only of the 54 deals recorded in H1 2023. By comparison, funding declined by 9% YoY, highlighting the widening gap between overall capital deployed and the number of companies securing investment.
Download now the MENA FinTech Venture Capital: The H1 2026 Review for the full funding and transaction trends, sub-industry analysis, geographic breakdown, and investor dataset here.
The increase sits entirely in rounds above $100M
The apparent resilience in MENA FinTech funding is being driven almost entirely by the largest transactions. Rounds above $100M grew year on year, while funding below that threshold contracted, meaning the market’s headline performance is increasingly dependent on a small number of outsized closes.
This is not unprecedented. MENA FinTech has seen periods of heavy concentration before, but the contrast is particularly clear when viewed against H1 2024, when no $100M+ round was recorded and funding reached its lowest level of the period. The H1 2025 split tells a similar story from the opposite direction: funding was significantly stronger in the first six months, before deal activity and capital deployment slowed sharply in H2.
The takeaway is less about the headline funding figure and more about where that capital is coming from. As fewer companies reach larger rounds, the strength of MENA FinTech funding increasingly depends on whether a handful of mega transactions close within the period.
FinTech's share of the region rose while the sector itself shrank
FinTech accounted for $617M of the $1.35B invested across MENA in H1 2026, taking a larger share of regional funding than in 2025. Yet this higher share did not come from growth within FinTech itself. Sector funding declined year on year, while the broader MENA market contracted at a faster pace. FinTech therefore captured a greater portion of a smaller regional funding pool, highlighting the sector's relative resilience rather than outright growth.
Why $617M does not settle the year
H1 alone does not determine where the FinTech market will finish the year. Historically, the first six months have accounted for anywhere from just over a third to more than half of annual funding, with deal activity showing a similarly wide range. As a result, annualising H1 figures provides a directional view of the market rather than a forecast for the full year.
The other variable is concentration. With the largest rounds accounting for a significant share of H1 funding, a handful of outsized transactions can materially shift the full-year picture. The absence of any $100M+ round in H1 2024 shows just how much the headline can change depending on when, and whether, those deals close.
For now, $617M tells us where the market stands, not where it is heading. The second half will determine whether MENA FinTech funding is stabilising or simply being propped up by a small number of large transactions, while the continued decline in deal activity remains a key trend to watch.
The report goes deeper into the funding picture, breaking activity down by quarter, transaction size, stage, country, industry and sub-industry, and investor, alongside FinTech exit activity across the period.
→ Access the Report Now.